Closing Costs for Home Buyers in Sarasota: What You Pay
The down payment isn’t the only cash you’ll need at closing. Your final amount depends on your loan, prepaid expenses, and how the contract allocates costs between buyer and seller.
It’s easy to focus on a home’s price and overlook the fees and prepayments involved in completing the purchase. This guide explains what closing costs may include in Sarasota County, which costs buyers and sellers typically pay, and how a purchase differs from a refinance. You’ll also learn why local title insurance customs matter, how loan-related taxes can affect your total, and which figures to review in your closing documents.
A clear view of the numbers helps you plan your cash needs and compare homes with confidence, whether you’re buying near downtown Sarasota or elsewhere in the county.
Key Takeaways
- Build your budget around more than the down payment: loan fees, prepaid expenses, and tax prorations can all affect the cash needed at closing.
- In Sarasota County, buyers customarily pay for the owner’s title policy and usually choose the closing agent, but the parties can negotiate a different arrangement.
- Separate the seller’s customary deed tax from the buyer’s mortgage-related taxes, and review how condo estoppel fees and special assessments are allocated.
- Compare purchase and refinance costs by looking at the services, taxes, and title charges each transaction requires.
Who Pays for Title Insurance in Sarasota County?
Title insurance protects against covered title defects related to property ownership. In Sarasota County, buyers customarily pay for the owner’s title policy, a practice followed in seven Florida counties. The parties can negotiate a different allocation under the FAR/BAR contract. Because the customary payer typically selects the closing agent, buyers usually choose the title company for the transaction.
Florida title insurance premiums use the same rates in every county, according to the Florida Office of Insurance Regulation.
An escrow deposit is money collected at closing for upcoming property expenses. Florida property taxes are paid in arrears, so taxes are prorated between buyer and seller at closing. Your lender’s escrow requirements and the closing date affect the amount collected.
A home inspection assesses a property’s visible condition, while a survey shows its boundaries and recorded improvements. Insurers may use these reports when evaluating a home’s risk and coverage.
Use a national calculator for an initial estimate, then review itemized figures for your specific purchase. Separate title insurance, prepaid insurance, property taxes, inspections, the survey, and escrow deposits so every expense has a clear place in your closing budget.
Who pays closing costs in Florida - buyer or seller?
Closing costs are transaction expenses allocated between buyer and seller according to local practice and the contract. In Sarasota, customary allocations can guide your estimate, but the parties may negotiate changes.
Buyer and Seller Cost Allocations
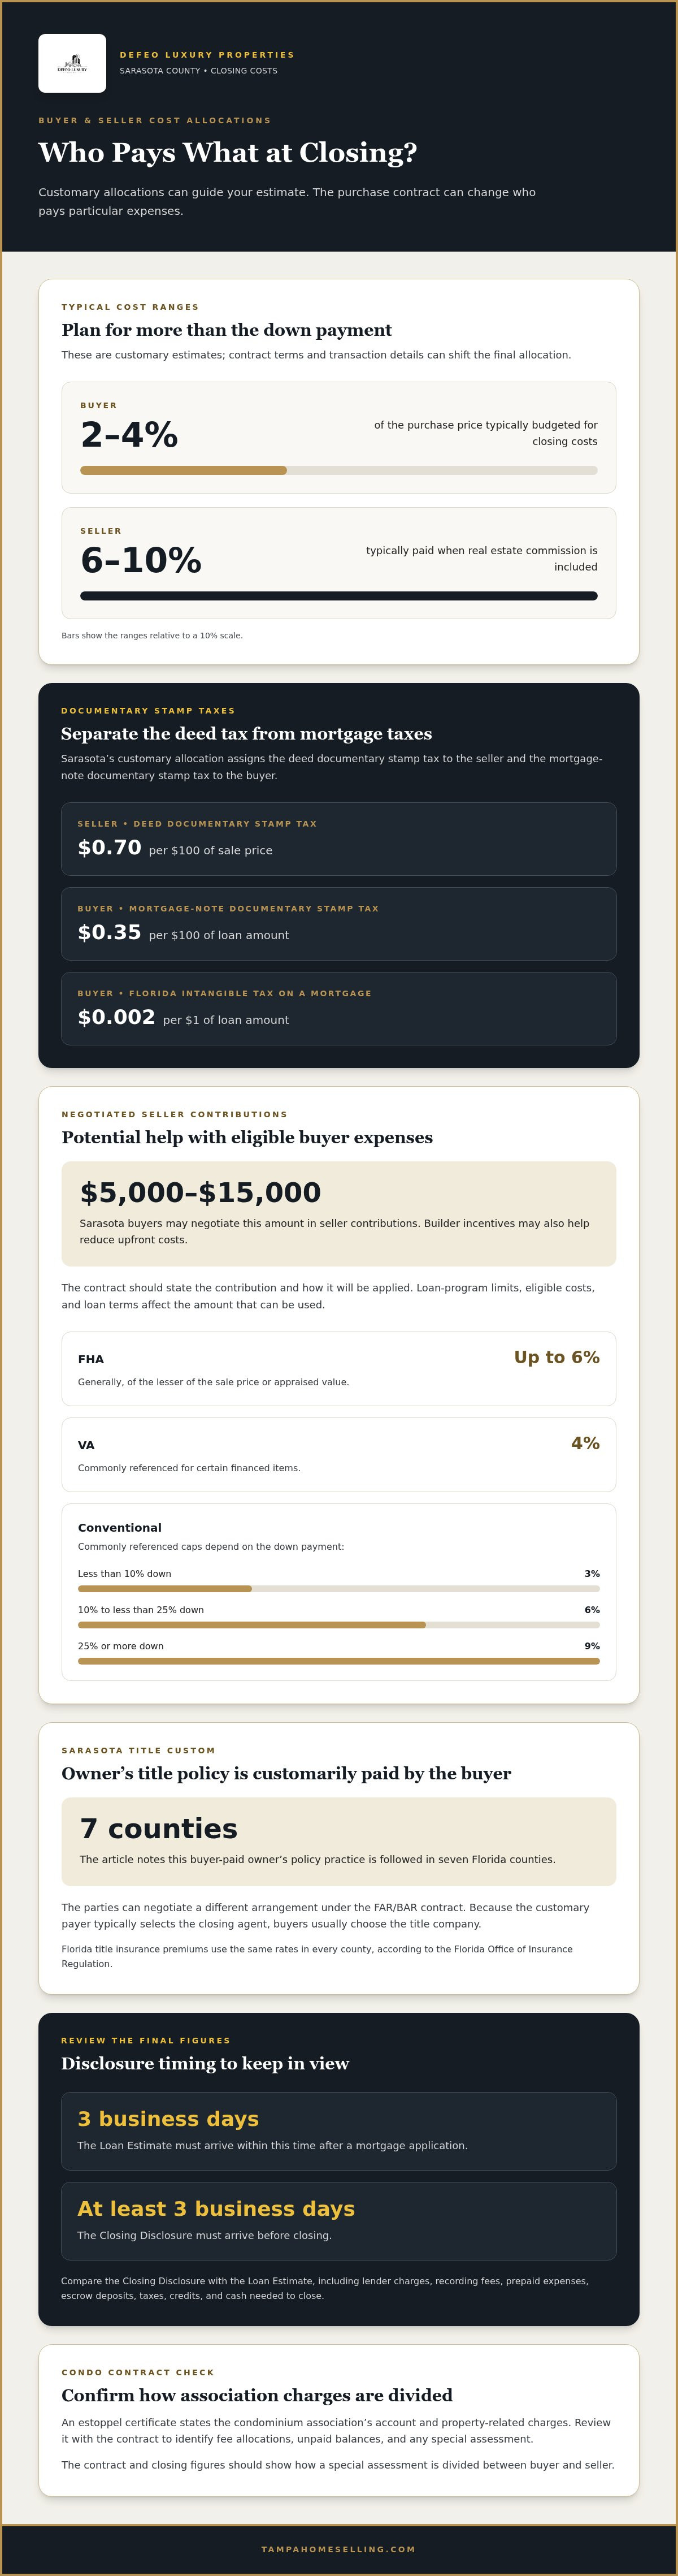
Cost allocation means assigning each closing expense to the buyer or seller. Sarasota sellers customarily pay the deed documentary stamp tax, while buyers pay documentary stamp tax on the mortgage note. The deed tax is $0.70 per $100 of sale price. Buyers typically budget 2-4% of the purchase price for closing costs; sellers typically pay 6-10% when real estate commission is included.
Recording fees depend on the document type and page count. A buyer’s estimate should separate lender fees and mortgage taxes from seller charges. The purchase contract can also change customary allocations, including who pays particular expenses.
Seller Contributions and Builder Incentives
A seller contribution is an agreed payment toward a buyer’s eligible closing expenses. Sarasota buyers may negotiate $5,000-$15,000 in seller contributions, while builder incentives can also help reduce a buyer’s upfront costs. The contract should state the contribution and how it will be applied.
Loan-program limits matter: FHA seller concessions are generally allowed up to 6% of the lesser of the sale price or appraised value. VA concessions are commonly referenced at 4% for certain financed items. Conventional caps are commonly 3% with less than 10% down, 6% with 10% to less than 25% down, and 9% with 25% or more down. Eligible costs and loan terms shape the usable amount.
The Buyer’s Closing Disclosure
A Closing Disclosure itemizes the final mortgage terms and transaction costs. It shows loan charges, prepaid expenses, escrow deposits, taxes, credits, and the cash needed to close.
As a Sarasota buyer, compare each line with the earlier Loan Estimate, including lender charges, recording fees, and seller contributions. The Loan Estimate must arrive within three business days of a mortgage application. The Closing Disclosure must arrive at least three business days before closing, giving you time to review the figures and spot changes.
Seller costs vary based on commission and negotiated credits. The contract and loan program determine which expenses shift between the parties.
Who pays the estoppel fee and any special assessment on a Sarasota condo?
A first-time buyer assistance program may help eligible purchasers with a down payment or closing costs. The program’s terms determine which expenses the funds can cover.
An estoppel certificate is a condominium association’s statement of account and property-related charges. Review it alongside the purchase contract to identify fee allocations, unpaid balances, and any special assessment. A special assessment is an association charge for a particular expense, such as a major repair. The contract and closing figures should show how that charge is divided between buyer and seller.
Mortgage closing costs are charges for services and expenses involved in arranging the loan. Sarasota County buyers can see lender charges, prepaid items, and taxes in the closing figures. The documentary stamp tax on a promissory note is $0.35 per $100 of loan amount, and Florida’s intangible tax on a mortgage is $0.002 per $1 of loan amount.
Recording fees cover filing property documents with the county. A settlement agent, generally a title company or attorney, facilitates the transaction.
Title costs can sometimes be reduced through applicable policy discounts. Florida allows a reissue rate on a new owner’s title policy when the property was insured within the previous three years. The Sarasota County calculator also lists a $25 simultaneous-issue lender’s title policy charge. Compare the itemized title charges and identify whether either option applies to your transaction.
Escrow is money collected at closing for expenses paid later, such as property taxes or insurance. Match the association’s estoppel statement against the contract, then compare assessment charges, mortgage taxes, recording fees, and escrow entries with the settlement statement. This helps distinguish association expenses from loan and county charges.
Eligible first-time buyers may receive help with closing costs, but the program’s terms determine which expenses it can cover.
Closing costs for home purchases and refinancing
Purchase closing costs are expenses for completing a property sale and arranging its mortgage. In Sarasota, buyers typically pay 2-4% of the purchase price in closing costs. That estimate can include lender charges, title services, recording, prepaid expenses, and taxes.
Mortgage costs are charges for services and expenses involved in obtaining a loan. Mortgage closing costs usually run 2-5% of the loan amount. Compare loan-based charges with purchase costs calculated from the home’s price.
Florida mortgage taxes are charges applied to certain loan documents. In Sarasota County, documentary stamp tax on a promissory note is $0.35 per $100 of loan amount. Florida’s intangible tax on a mortgage is $0.002 per $1 borrowed. Property taxes and insurance premiums may also appear as prorations or escrow deposits.
Refinance closing costs are expenses involved in replacing an existing mortgage with a new loan. They depend on the new loan amount, lender services, title work, and prepaid items. Review the Loan Estimate and closing documents to see how each charge affects your expected savings or payment change. A lower rate alone doesn’t show the full cost of refinancing.
Title insurance may affect either transaction’s total. Florida allows a reissue rate on a new owner’s policy when the property was insured within the previous three years. For a refinance, compare title charges with the existing policy information and review whether a lender’s title policy is included. The Sarasota County calculator lists a $25 simultaneous-issue lender’s title policy charge.
Use the contract and loan documents to compare the purchase price, mortgage amount, property taxes, and insurance premium. This side-by-side review separates one-time purchase expenses from costs tied to the new loan.
DeFeo Luxury Properties: 30-Day Home Selling System
DeFeo Luxury Properties’ 30-Day Home Selling System combines AI-driven buyer targeting and pre-listing inspections to support sellers preparing for a move. If you’re planning to sell before buying in Sarasota, this approach connects your sale strategy with the costs and timing of your next purchase.
Buyers can explore the VIP Buyer Program for access to off-market listings, a one-year home warranty, and the Love It or Leave It Guarantee. Sellers considering another route can review the Instant Cash Offer. Each option suits a different situation, whether you’re preparing a home for market, seeking purchase opportunities, or weighing an offer.
To plan your next step, visit the home valuation page.
Make Your Next Move With a Clear Plan
Use what you’ve learned about closing costs for home buyers in Sarasota to shape a purchase plan around your broader move. Decide what needs to happen first: buying, selling, or weighing an offer on your current home. A timely conversation can help connect those decisions and keep your priorities in view.
DeFeo Luxury Properties offers the VIP Buyer Program for buyers, the 30-Day Home Selling System for sellers, and an Instant Cash Offer for homeowners considering another sale option. Choose the path that best matches your next step, then discuss how it fits your real estate goals.
Ready to talk through your plans? Contact DeFeo Luxury Properties and take the next step with confidence.
Frequently Asked Questions
What Percentage Are Closing Costs in Sarasota County?
Closing costs for home buyers in Sarasota typically equal 2-4% of the purchase price. A cash buyer typically budgets about 1-2%, since there’s no mortgage-related tax or lender charges. Your total depends on the loan amount, title charges, prepaid expenses, and negotiated credits. Keep the down payment separate from closing costs when planning funds, since it is a separate part of the cash needed to complete your purchase.
Can I negotiate seller concessions to cover closing costs?
Yes, buyers and sellers can negotiate a seller contribution in the purchase contract. The agreed credit may cover eligible transaction expenses, but it doesn’t automatically reduce the down payment or provide cash beyond allowable costs. Loan-program limits and lender rules determine which expenses qualify. Before relying on a contribution in your budget, make sure the contract states the amount and which costs it will offset.
How are property taxes prorated at a Sarasota closing?
Property taxes are prorated by dividing responsibility between the seller and buyer for their respective ownership periods. The closing statement records a credit or charge so each party covers the appropriate share, even though the tax bill is paid later. Check the tax year, closing date, and assessed property details used in the calculation. These inputs affect the adjustment and help explain why the closing credit may differ from a future bill.
What are documentary stamp tax and intangible tax on a Florida closing?
Documentary stamp tax applies to deeds and certain written obligations, while intangible tax can apply to a mortgage. In Sarasota County, the mortgage-note stamp tax is $0.35 per $100 borrowed, and intangible tax is $0.002 per $1 of loan amount. A cash purchase has no mortgage note or mortgage intangible tax.
What is the doc stamp tax on the deed?
Sarasota County’s deed documentary stamp tax is $0.70 per $100 of sale price, customarily paid by the seller. The parties may negotiate a different allocation in the contract, so review the settlement statement to see which side is charged. This deed tax is separate from documentary stamp tax on a buyer’s mortgage note.
Why is my cash to close higher than the closing cost estimate I found online?
Cash to close includes more than closing costs: it also reflects your down payment, minus applicable deposits and credits. Prepaid insurance, escrow deposits, tax prorations, and final lender figures also affect the amount. Compare the estimate with your Closing Disclosure line by line to identify changes.